

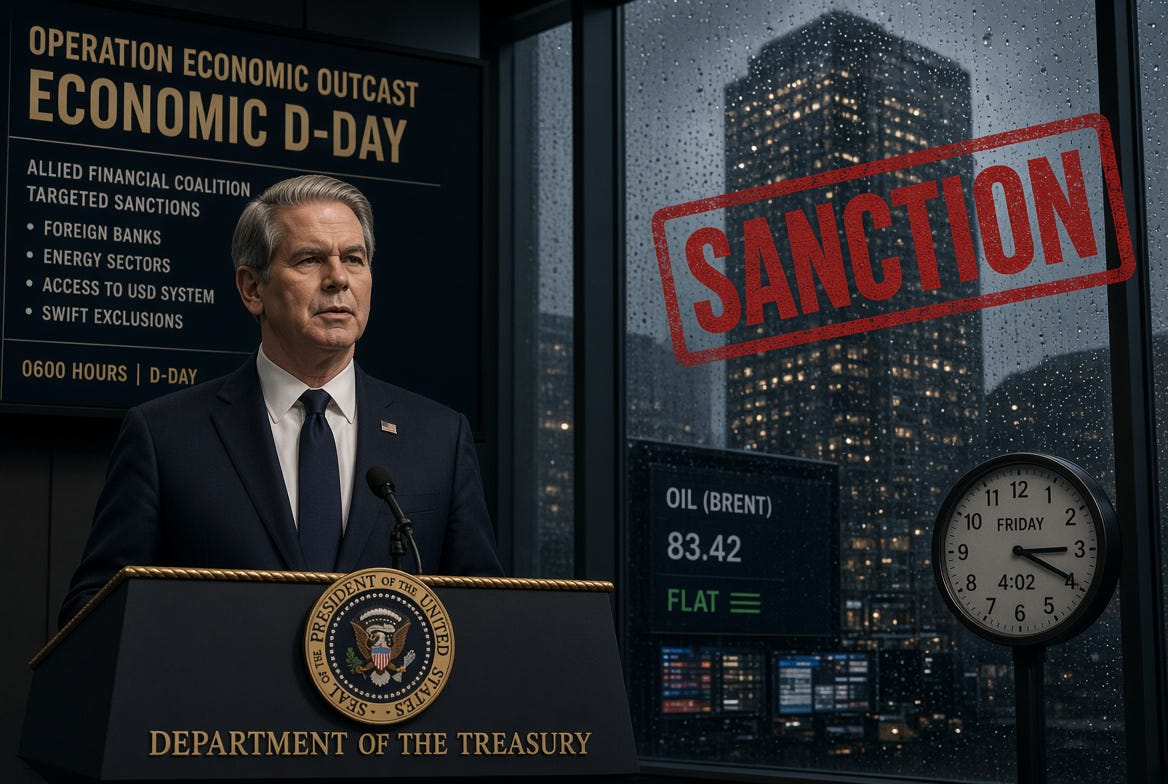
This past Monday, Treasury Secretary Bessent launched Operation Economic Outcast and billed it as the next phase of the conflict: “Economic D-Day.” The package featured sectoral determinations on digital assets, gold, aviation, technology, and shipping comprised of roughly sixty designations. Secondary-sanctions risk widened as a result with Bank Melli branches told to go dark and Bessent forecasted enforcement action on a “major financial institution” by the end of the week.
That is not nothing. It is also not “D-Day”.
Using the “D-Day” terminology, the landing happened but the breakout did not. Specifically, a systemically important clearer has not been removed from the dollar system at the time of this writing. China, still the buyer of the overwhelming share of whatever Iranian oil gets out, said on Tuesday that cooperation with Tehran “should not be interfered with” and that it would “take all necessary measures.” For markets, oil did not reprice as if the oil-clearing bank had just been cut off or was about to be, imminently.
The lead-up to these new economic actions came with the “power plant and bridge day” register most observers have already priced: maximum language, bounded or non-existent next step. To that end, Bessent stated he does not want to “blow up the global financial system” which signals to observers that he would unlikely take severe or systemic action. Hitting a no-name intermediary is cheap, but hitting an actual oil-clearing bank is a second war that sits in front of a Trump–Xi meeting and on top of a Treasury market this publication has already argued is a material part of any Iran-related consideration set.
What Monday likely was
As outlined in the one-trick pony note, the U.S. playbook has been to negotiate, escalate, threaten, then pull back. Monday’s presser is aging in a way that shows this playbook being applied to the economic campaign as well - existential branding paired with a payload that seems more like a warning shot than a course of action the U.S. is willing to follow through on.
The IRGC watched the same comments and resultantly stayed in their defiant posture. However, civilian Iranian officials say they are trying to halt an inflation spiral and keep shelves from emptying. The pumps and the rial suggest civilian leadership has reason for concern: kilometer-long petrol queues, a daily gasoline shortfall on the order of 14–15 million litres, the rial through two million to the dollar, inflation near 90 percent and food worse. To garner support, the IRGC cites multi-decade sanctions survival and a Chinese buyer that has already refused to participate in damaging actions against Iran. The net is a regime that still believes it has a safer economic harbor than Washington’s commentary implies.
Alongside this, the official U.S.–Iran diplomatic track reads as dead. Washington rebuffed a return to the June MOU and continues to say there is no diplomacy underway, while Iran is not advertising a live or active channel either. Third-party traffic continues — Pakistan’s army chief was in Tehran on Monday — but it is more likely than not another episode of mediation theater and hope that delay (time) creates space for further diplomacy. The “significant progress” comments from mediating nations have lost their bid, no differently than U.S. escalatory threats.
Taken together: existential language spent on a first-day package, an Iran with sanctions-evasion muscle memory and a Chinese buyer that rejected the ask, and a diplomatic track that exists mostly as content. Enter a stalemate absent a move that changes the oil math.
The stalemate problem
From Washington’s chair, time is doing the work of munitions. That was the argument in The IRGC’s Escalation Trap: Iran, not the United States, sits in the structurally tighter trap due to having less optionality. The blockade, the internal inflation, and the closing of the post-succession unity window are compounding. Pezeshkian has been blunt about household pain inside Iran — the same constraint laid out in The Path of Least Resistance That Isn’t. Iranian data tends to be opaque but the petrol queues are not. On the question of economic pressure, the current approach U.S. approach is working.
So how do you break a stalemate when every departure from status quo carries material economic and military risk?
If you are the United States, you don’t — unless the threat that underwrites the status quo starts to look fake. Status quo is delivering what Washington wants: material economic pain, social unrest, and a security apparatus that is clamping down rather than seeking an off-ramp. Protesters from the winter unrest are still being executed, including in public. The IRGC is being forced to first lie, then explain not to believe your lying eyes, then to say there are five lights. That path can work until reality demonstrates it to be false.
Trump, Bessent, or any other American actor does not need a kinetic restart if compounding has a viable chance of working. Communications can insist Iran is strong with the petrol lines telling a different story. For Trump, a slow grind is also the midterm-compatible path. Rubio and others have indicated economic levers will be the preferred manner of engagement at least through November. Course and speed have been plotted around political realities, as many have expected.
Three options, same split
That leaves the ball in Iran’s court. At a high level, Iran remains with three options:
Concede and take a deal on U.S. terms.
Hold status quo and bet that U.S. political will, the midterms, or fuel-price pain at home sends Washington off the field.
Raise the intensity of the campaign already underway — Hormuz rules, drones, shipping pressure, lawfare — and try to drive the United States out by raising the cost.
Civilian leadership has shown a preference for option one as the path most likely to relieve the household economy Pezeshkian wants to fix. Option two is defiance. Option three is not what the civilian track desires as it seeks to avoid further costs associated with a wider war.
However, the IRGC apparatus that holds functional power has given no sign it wants a deal. To wit, Iranian parliament is advancing a bill that would further write Hormuz regulation — fees, permits, sovereign framing — into domestic law. State-linked media put a $10 million bounty on the head of a sitting U.S. president’s son (though later denied). Pressure on shipping has continued with Iranian drones or missiles striking merchant vessels regularly. None of that is option one or a clean option two. In practice, the third option of continued hostilities becomes Iran’s official stance by default - regardless of the commentary from civilian leadership.
This is Iran’s escalation trap in operational form. The civilian leadership talks paths away from further aggression while the IRGC leans on threats and kinetic pressure. Option two could work for a time, but it does not appear certain that the average Iranian will suffer indefinitely for IRGC benefit. Internal unrest is a problem that Tehran has long feared and it moves closer if Bessent’s measures land on a real oil clearer or, even without that, tightening isolation of Iranian finances.
The constraint is the second war
Bessent cannot “BACO” the economic warfare strategy and expect it to be successful on a timeline that the U.S. can accept. The blockade alone may work over a longer horizon, but likely runs into the U.S. election and economic clocks via higher energy prices and dwindling SPRs simultaneously. Much like the military engagement, a “BACO” before the midterms would defang another lever of U.S. offensive credibility absent a tangible result from the threat. Showing you will not fight kinetically, then demonstrating you will not make good on the economic threat that replaced the fighting, leaves you low on ammunition and at risk of further losing control in the information and optics spaces.
That is the one-trick pony problem applied to Treasury. Escalation language has too often outrun matching action, and Iran now says so out loud. A threat has to be something you can do and be something you are willing to do.
The week is not over and the “major-institution” designation can still land. It would not be surprising to see the action come after market close on Friday as the administration has historically favored escalating when equity markets are closed. As of this writing, the higher-probability read seems to be the one we have been running: maximum language, bounded first step, decision deferred to China and the long bond. Markets, so far, seem to be trading that version.
That could change quickly. For the moment, treat “Economic D-Day” as a beach landing, not a breakout.
Disclaimer: This note is provided for informational purposes only and does not constitute investment, financial, or legal advice. The information contained herein is based on current market observations and analysis, which are subject to change without notice. All investments involve risk, including the loss of principal. We do not provide personalized recommendations, and readers should conduct their own due diligence or consult with a qualified professional before making any investment decisions.